All You Need to Know About Government Bonds
📅 2026 Update: Key Changes in U.S. Bankruptcy Law
Since the original article was written, there have been important updates in U.S. bankruptcy law. While the core chapters of bankruptcy, like Chapter 7 and Chapter 11, remain the same, more resources are now available for those considering filing. The earlier article continues further down the page, providing foundational information about government bonds.
🔍 Recent Resources for Bankruptcy Assistance
New and updated resources can help individuals navigate bankruptcy more effectively. The U.S. Courts Official Website and the U.S.
Department of Justice provide detailed information on procedures and forms. These resources are critical for understanding what is required when filing for bankruptcy.
- 📄 U.S. Courts Official Website: This site gives comprehensive details about bankruptcy chapters and the necessary forms. It’s a reliable starting point for anyone looking to file.
- ⚖️ U.S. Department of Justice – U.S. Trustee Program: This program offers guidance on eligibility and the filing process. It helps clarify the steps involved for individuals seeking bankruptcy.
🛡️ Legal Aid Organizations
Legal aid organizations have increased their outreach and services. They provide free or low-cost help to individuals facing bankruptcy. Many states have legal aid societies dedicated to assisting those in financial distress.
📝 National Consumer Law Center (NCLC)
The NCLC offers resources specific to consumer bankruptcy. They focus on advocacy and education, helping individuals understand their rights and options in bankruptcy.
📌 Key Updates to Remember
- New resources are available for bankruptcy assistance.
- The U.S. Courts Official Website is crucial for understanding procedures.
- Legal aid organizations provide free support.
- The NCLC focuses on consumer bankruptcy rights.
- Up-to-date information is essential for navigating recent changes.
💡 Tips for Navigating Bankruptcy
It’s important for individuals to review their unique situations with their attorney. Understanding personal circumstances can lead to better decisions during the bankruptcy process.
🏗️ Understand Bankruptcy Chapters
Each bankruptcy chapter serves a different purpose. Familiarizing yourself with Chapter 7, Chapter 11, and Chapter 13 can help determine which option fits your needs best.
📅 Keep Track of Deadlines
Filing for bankruptcy involves specific deadlines. Missing these deadlines can complicate the process and may result in a denial of your case.
📃 Gather Necessary Documents
Having all required documents ready can streamline the filing process. This includes financial statements, tax returns, and a list of debts.
🔍 Research Legal Assistance
Look for local legal aid organizations that offer support. Many provide free or low-cost services to those who qualify.
🏦 Explore Financial Education Resources
Educating yourself about finances can be beneficial. Many nonprofits offer workshops on budgeting and money management, which can help after bankruptcy.
🏆 Free Options Ranked by User Reviews (2026)
Currently, no national paid services have met the review threshold for assistance in bankruptcy. Instead, this section highlights free government and nonprofit resources that can help.
🥇 1. U.S. Courts Official Website
This website is a primary source for information on bankruptcy laws and procedures. It covers all chapters, forms, and filing requirements, making it an essential tool for anyone considering bankruptcy.
🥈 2. U.S. Department of Justice – U.S. Trustee Program
The U.S. Trustee Program provides information about the bankruptcy process. It offers guidance on eligibility and what to expect when filing, which can ease anxiety for first-time filers.
🥉 3. National Consumer Law Center (NCLC)
The NCLC is a nonprofit organization that focuses on consumer rights. It provides resources and support for individuals facing bankruptcy, helping them understand their rights and options.
4️⃣ Legal Aid Organizations
Many states have legal aid societies that offer free or low-cost help. They assist individuals in navigating the complexities of bankruptcy and may provide legal representation.
🔎 What to Check Before Paying for Help
- 💰 Understand the costs of services offered.
- 📜 Verify the credentials of anyone providing assistance.
- 💬 Read reviews and testimonials from past users.
- 🔍 Ensure the provider specializes in bankruptcy law.
❓ Frequently Asked Questions
❓ What is a means test in bankruptcy?
The means test determines eligibility for filing Chapter 7 bankruptcy. It assesses income compared to the median income in your state.
🕒 How long does the bankruptcy process take?
The duration varies by chapter. Chapter 7 typically takes about 3 to 6 months, while Chapter 13 can last 3 to 5 years.
💳 Can I keep my credit cards after filing?
Generally, credit card debt may be discharged in bankruptcy. However, you may need to close credit card accounts to prevent further debt.
📈 How does bankruptcy affect my credit score?
Bankruptcy will negatively impact your credit score. It can stay on your credit report for up to ten years, affecting future credit opportunities.
🛑 Is there an automatic stay in bankruptcy?
Yes, an automatic stay goes into effect once you file. This halts most collection actions against you, providing temporary relief.
📑 Can I discharge student loans in bankruptcy?
Discharging student loans in bankruptcy is challenging. You must prove undue hardship to qualify for discharge.
⚖️ Recent Court Cases Related to Bankruptcy
Recent court rulings have further clarified aspects of U.S. bankruptcy law, impacting how cases are handled. These decisions can affect what individuals may experience during bankruptcy.
- Court denies wife's petition to discharge guardian ad litemDistrict Court of Appeal of Florida · December 20, 2023
- Arizona court rules on divorce debt and bankruptcy caseCourt of Appeals of Arizona · October 2, 2026
- Court Denies Stay in Bankruptcy Case Involving Medical FirmDistrict Court of Appeal of Florida · September 2, 2020
- Court reverses job search requirement for debtor in caseSupreme Court of The Commonwealth of The Northern Mariana Islands · February 22, 2011
For more recent rulings, feel free to browse more rulings on the news page.
End of October 2026 Update
When a country needs to obtain financial resources in order to fund important projects, it may issue government bonds. Government bonds are purchased from a government by an individual. The funds that a government receives from the purchase can be utilized as needed or desired. However, like a loan between a bank and a consumer, the government will be required to repay the lender for the loan.
Government bonds are not amortization loans, and therefore, repayment for the initial loan value will occur at the end of the loan duration. An individual that has purchased a government bond will receive interest payments from the borrower on numerous occasions throughout the length of the loan. The interest rate attached to a government bond will be fixed.
Typically, a lender will receive interest payments twice a year, though this may vary based on the conditions of the bond. However, an individual will not be compensated for the full value of the loan until the bond's specified maturation date.
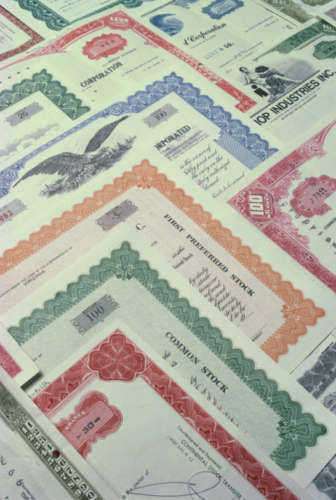
Government bonds differ from foreign currency bonds because, while a foreign currency bond is issued by a government, a government bond is only issued to consumers within the country. There are similarities, however. Foreign currency bonds are issued by a government to investors throughout the world and remain in the currency of the issuing country, while a government bond issued by the United States Treasury will be purchased by citizens of the United States in the U.S dollar, and thus, also expressly in the currency of the country of origin.
Government bonds are generally considered to be the most secure type of bond that an individual can purchase, as they represent an entire country. A government bond is usually a safer investment than a municipal bond or an international bond. However, if an investor resides in a developing country that maintains an unstable government, then he/she should be wary about the possibility of a government defaulting on a government bond.
The most secure government bonds are issued by the United States, the United Kingdom, Germany, France, Japan, and Italy. Bonds from the United States, otherwise known as treasury bonds, are often perceived to be the most secure investments of them all.
Because purchasing a government bond is a fairly safe investment, the interest rate attached to these types of loans are often low. Therefore, people often choose to take part in more risky investments in order to yield a larger profit. Despite this, many investors appreciate the security that is associated with government bonds.
If an investor wishes to collect on the value of a loan before the designated maturation date, he/she may choose to sell the bond on a secondary market. The individual who purchases the bond from the original lender will then receive the remaining interest payments, along with the primary value of the loan at the date of maturation.
In the United States, a government bond may be obtained from the Department of the Treasury. In fact, bonds may be purchased online at the Department's website.