Facts About Annual Percentage Rate
📅 2026 Update: Changes in U.S. Bankruptcy Law
Since the original article was published, there have been important updates regarding U.S. bankruptcy law. Though the core principles remain the same, it is essential to be aware of recent developments and resources available for those considering bankruptcy. The earlier article continues further down this page, covering foundational aspects of bankruptcy.
📜 Recent Changes in Bankruptcy Resources
The landscape of bankruptcy resources has changed. Access to reliable information about bankruptcy processes is crucial. The **U.S.
Courts Official Website** remains a key source for detailed information on bankruptcy chapters and filing procedures. This site continues to be updated with the latest forms and guidelines to help users navigate the system.
🏛️ U.S. Department of Justice – U.S. Trustee Program
The U.S. Trustee Program provides guidance on bankruptcy laws and filing processes. It is essential for individuals to understand the eligibility requirements for various bankruptcy chapters.
This resource offers information on what to expect during the bankruptcy process, ensuring that individuals are better prepared.
🆓 National Consumer Law Center (NCLC)
The National Consumer Law Center (NCLC) is a nonprofit organization dedicated to consumer issues, including bankruptcy. They provide resources and assistance geared toward helping individuals understand their options. This organization is particularly useful for low-income individuals and those unfamiliar with bankruptcy laws.
🏥 Legal Aid Organizations
Many states have legal aid organizations that offer free or low-cost legal assistance. These groups help individuals who may not be able to afford traditional legal services. They can provide support throughout the bankruptcy process, ensuring that individuals receive the help they need.
📌 Key Takeaways
- 📌 The U.S. Courts Official Website provides essential updates on bankruptcy procedures.
- 📌 The U.S. Trustee Program offers guidance on eligibility and filing for bankruptcy.
- 📌 The NCLC aids consumers with valuable resources.
- 📌 State legal aid organizations can provide free or low-cost assistance.
- 📌 Staying informed is crucial for individuals considering bankruptcy.
💡 Tips for Navigating U.S. Bankruptcy Law
It is important to discuss your specific situation with an attorney. They can help clarify your options and guide you through the process.
🔍 Understand Your Bankruptcy Options
Explore different types of bankruptcy, such as Chapter 7, Chapter 11, and Chapter 13. Each type serves distinct purposes and has different eligibility requirements. Knowing which chapter fits your needs is essential for making informed decisions.
⏳ Be Aware of Deadlines
Filing for bankruptcy involves various deadlines. Missing a deadline can delay your case or affect your eligibility. Stay organized and mark important dates to avoid complications.
📄 Complete Necessary Forms
Accurate completion of bankruptcy forms is critical. Errors or incomplete information can lead to delays or dismissals. Double-check all forms before submission to ensure that everything is accurate and up to date.
💬 Seek Help from Local Resources
Utilize local resources like legal aid organizations for guidance. These organizations often assist individuals with low incomes and can provide valuable support during the bankruptcy process. They can help you understand your rights and responsibilities.
🛑 Avoid Bankruptcy Scams
Be cautious of companies that promise quick fixes or charge high fees. Research any organization before seeking help. Relying on reputable sources, such as government websites, can protect you from scams.
🏆 Free Options Ranked by User Reviews (2026)
No paid national service met the review threshold for bankruptcy assistance. Instead, this section highlights valuable free government and nonprofit resources that can provide support.
🥇 1. U.S. Courts Official Website
The U.S. Courts Official Website offers comprehensive information on bankruptcy chapters, forms, and procedures. It is the go-to source for anyone looking to understand the bankruptcy process.
The site is updated regularly, ensuring that users have access to the latest information.
🥈 2. U.S. Department of Justice – U.S. Trustee Program
The U.S. Trustee Program provides guidance on eligibility and the filing process. This resource is essential for individuals exploring their bankruptcy options.
It helps users navigate the complexities of bankruptcy laws and procedures.
🥉 3. National Consumer Law Center (NCLC)
The NCLC focuses on consumer rights and offers resources related to bankruptcy. Their materials are designed to help individuals understand their rights and navigate the bankruptcy process effectively. This organization is particularly useful for low-income individuals.
4️⃣ Legal Aid Organizations
Local legal aid organizations offer free or low-cost legal assistance to those in need. These groups can help individuals understand their options and provide support throughout the bankruptcy process. They are vital resources for low-income individuals seeking legal help.
🔎 What to Check Before Paying for Help
- 🔍 Verify the credentials of any organization you consider.
- 🔍 Look for reviews and ratings from previous clients.
- 🔍 Ensure the service is transparent about fees and processes.
- 🔍 Confirm that the organization specializes in bankruptcy.
❓ Frequently Asked Questions
🤔 What is the means test in bankruptcy?
The means test helps determine eligibility for Chapter 7 bankruptcy. It compares your income to the median income in your state. If your income is below the median, you may qualify for Chapter 7.
📅 How long does the bankruptcy process take?
The duration of the bankruptcy process varies. Typically, Chapter 7 cases take about three to six months to complete. Chapter 13 cases may last three to five years, depending on the repayment plan.
📄 What are bankruptcy exemptions?
Bankruptcy exemptions allow you to keep certain assets during bankruptcy. These exemptions vary by state and can include your home, car, and personal belongings. Understanding these can help protect your essential assets.
🏦 How does bankruptcy affect your credit score?
Filing for bankruptcy can significantly impact your credit score. A Chapter 7 bankruptcy can remain on your credit report for up to ten years, while Chapter 13 can stay for seven years. This can affect your ability to obtain credit in the future.
🚫 Can I file for bankruptcy more than once?
Yes, you can file for bankruptcy multiple times. However, certain time limits apply between filings. For example, if you file for Chapter 7, you must wait eight years before filing again under the same chapter.
📞 What resources are available for bankruptcy help?
There are various resources available, including the U.S. Courts Official Website, the U.S. Trustee Program, and legal aid organizations.
These resources provide valuable information and assistance for individuals navigating bankruptcy.
⚖️ Recent Cases Relating to Bankruptcy
Recent court rulings have clarified aspects of U.S. bankruptcy law. These rulings can affect how individuals understand and navigate their bankruptcy options.
- Court reverses mechanic's lien discharge in New York caseAppellate Division of the Supreme Court of the State of New York · June 9, 2026
- Connecticut Court Denies Discharge for Marvin NarcisseConnecticut Appellate Court · June 9, 2026
- Texas court abates appeal amid bankruptcy filing by appellantTexas Court of Appeals, 3rd District (Austin) · June 16, 2026
- Texas Court of Appeals stays Starkey v. Hiebler case due to bankruptcyTexas Court of Appeals, 3rd District (Austin) · June 19, 2026
For more recent rulings, browse more rulings on the news page.
End of October 2026 Update
When an individual shops around for a new motor vehicle, he/she will constantly hear the term "APR." Car commercials proudly display APR costs and make it a point to emphasize a low APR. Despite the prevalence of the term, many individuals are still uncertain of its meaning.
APR, or annual percentage rate, refers to the amount of interest that a debtor will be required to pay on a loan every year. Understanding this term is not just important when purchasing a motor vehicle. Credit cards, home mortgages, and most other types of loans all have an annual percentage rate attached.
A lender grants an applicant a loan based on the premise that he/she will repay the loan plus interest. The debtor will pay the principle to cover the initial value of the loan and the interest that is paid, which serves as the profit to the creditor.
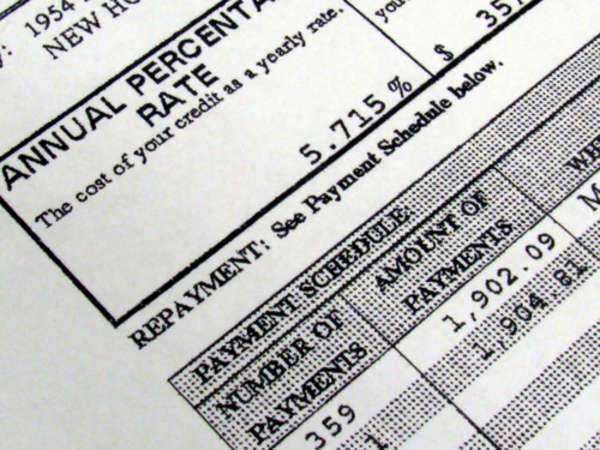
The annual percentage rate will vary from one loan to another, as well as from one borrower to another. If an individual has warranted a sub-par credit history as a result of failure to regularly pay previous debts, the annual percentage rate that is attached to a loan secured by him/her may be higher than the APR of other debtors.
A higher annual percentage rate may cause complications for an individual that has previously experienced trouble repaying his/her debts. A high APR will result in larger monthly payments.
If a debtor is having financial difficulties, high monthly payments will make it more difficult for a debtor to meet his/her financial obligations, and he/she will end up paying the lender much more money than the initial value of the loan. Therefore, it is important for an individual to research different lenders in order to find the lowest possible APR.
Interest payments are incorporated into a borrower's monthly payments. In the case of credit cards, if an individual makes manageable purchases and pays off the debt every month, the interest that he/she is required to pay will generally be more reasonable. However, if the borrower maxes out his/her credit card and makes only the minimum payment every month, he/she will end up paying a notable amount in interest.
The longer a loan duration, the more interest an individual will be required to pay on the loan. For example, if a borrower accumulates a debt of $2,000 and is required to pay 7% APR, he/she will save a great deal of money if the debt is paid off quickly. It the borrower only pays a small portion of this debt each month, he/she will be required to pay a certain percentage of interest every month that the debt remains.
Failure to make timely monthly payments will result in higher interest rates. An individual that has a positive credit history may enjoy an APR as low as 7%. However, if a debtor fails to make his/her monthly payments on time, the interest rate may rise to over 27%.